
According to IDC’s Worldwide Semiannual Software Tracker (April 2026), which measured the global CRM applications market for 2025, the leading vendors held the following revenue shares:
| Vendor | Market Share (%) |
|---|---|
| Salesforce | 20.0 |
| Oracle | 4.1 |
| Microsoft | 4.0 |
| Adobe | 3.4 |
| SAP | 3.1 |
| All Others | 65.4 |
Salesforce continues to lead the CRM market by a wide margin. Its 2025 CRM revenue was nearly five times that of its nearest competitor, and IDC has now ranked Salesforce the #1 CRM vendor worldwide for 13 consecutive years. Salesforce also remains #1 in Sales applications (14 consecutive years), Customer Service (13 years), and Marketing (7 years).
What Changed in 2025
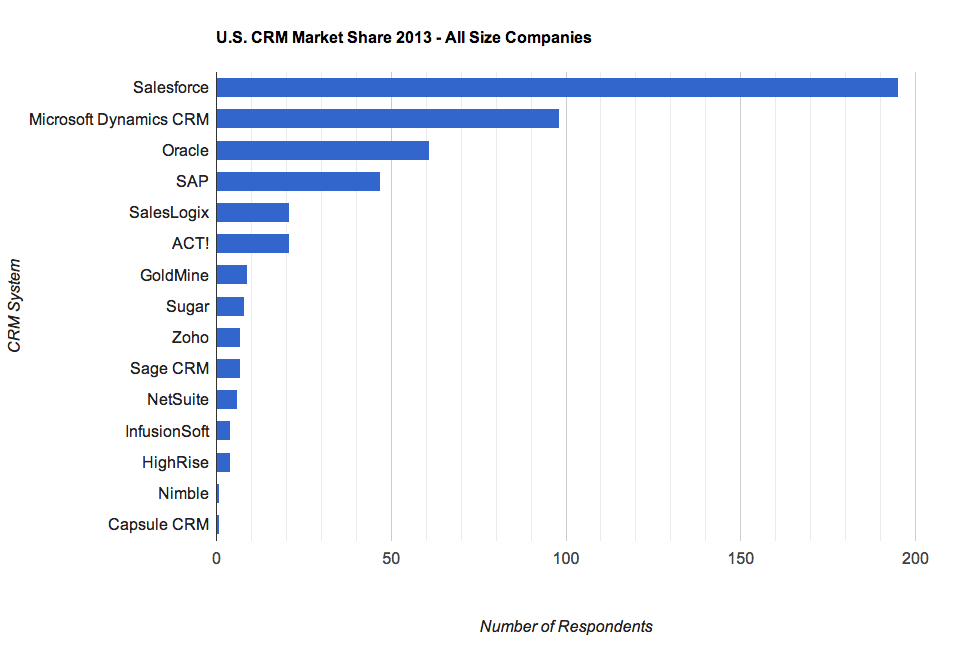
Comparing the newest IDC numbers to last year’s data (and to our original 2013 survey), several shifts stand out:
- Oracle is now the #2 CRM vendor. Microsoft had held that spot since 2022, but its share fell from 5.2% to 4.0% in 2025 while Oracle held steady at 4.1%. Oracle’s pitch that customers’ back- and middle-office data already lives on its platform (so their CRM and AI should too) appears to be resonating. Oddly, Microsoft still reports double-digit Dynamics 365 growth, though that figure blends ERP with CRM.
- Salesforce’s share slipped again, from 20.7% in 2024 to 20.0% in 2025. As in prior years, that reflects a faster-growing market, not a shrinking Salesforce. Its lead over the field actually widened, from about four times the #2 vendor’s CRM revenue to nearly five.
- IDC began tracking a brand-new category, “Agent Build and Deploy,” which it says is in a state of hypergrowth. Salesforce grew fastest in the category and took the #2 position with a 17.5% share, a sign of how quickly the CRM and AI-agent markets are converging.
- HubSpot keeps compounding. It ended June 2026 with 306,446 paying customers, roughly double Salesforce’s reported 150,000+, after 2025 revenue of $3.13 billion (up 19%). By our math, that’s just under 3% of the market, though HubSpot flagged softer demand in Q2 2026.
- The “All Others” segment keeps expanding, from 46% in 2007 to 65.4% in 2025. Newcomers keep arriving: 18 of the 65 vendors in our CRM launch timeline launched in 2019 or later. Zoho lands here too: its entire app suite booked about $830 million in fiscal 2025, so its CRM share is under 1%.
The Share Shift Scorecard: 2021 vs. 2025
One year of data can mislead, so we lined up IDC’s 2021 and 2025 figures and did the math.
| Vendor | 2021 | 2025 | Relative change |
|---|---|---|---|
| Salesforce | 23.8% | 20.0% | -16% |
| Oracle | 5.1% | 4.1% | -20% |
| Microsoft | 5.3% | 4.0% | -25% |
| Adobe | 3.8% | 3.4% | -11% |
| SAP | 5.4% | 3.1% | -43% |
| Top five | 43.4% | 34.6% | -20% |
| All Others | 56.6% | 65.4% | +16% |
Three things jump out. SAP lost the most ground, shedding 43% of its share. The top five gave up 8.8 points. And a point is worth real money: IDC’s 2024 figures ($21.6 billion for Salesforce at 20.7%) imply a roughly $104 billion market, so each point is worth over $1 billion a year. At their 2021 share, the top five would be booking more than $9 billion a year that now goes to everyone else.
CRM Market Size and Growth
Market size estimates depend on how each firm defines “CRM.” For 2025 they range from $76.9 billion (IMARC Group) to $112.9 billion (Fortune Business Insights), which projects $126.2 billion for 2026. North America accounts for about 32% of that total.
Longer-term forecasts range from Grand View Research’s $161.3 billion by 2033 to Fortune Business Insights’ $321 billion by 2034, with most analysts expecting 8% to 12% annual growth, driven by generative AI and autonomous agents.
AI Agents Are Now the Battleground
In 2025, every major CRM vendor embedded AI agents into its core product. In 2026, agents became a measurable market of their own, as IDC’s new category makes official. Here’s where the major vendors stand:
- Salesforce has made Agentforce the center of its product strategy, with Data 360 (formerly Data Cloud) feeding its agents. Agentforce ARR topped $1.5 billion by July 2026, and Salesforce’s deal for m3ter, a consumption-billing platform, signals that usage, not seats, is becoming the pricing unit.
- Oracle continues to build out its AI Agent Studio, arguing that agents perform best where CRM sits alongside ERP, HCM, and supply chain data in one Fusion Cloud suite.
- Microsoft leans on Copilot across Dynamics 365 and its integrations with Microsoft 365, Teams, and Power Platform.
- HubSpot has expanded Breeze AI and Breeze Agents platform-wide, emphasizing out-of-the-box usability over heavy configuration.
- Adobe is adding AI agents to its Experience Cloud for marketing personalization.
- SAP ties its Customer Experience suite to operational data through Joule-powered journey orchestration.
Disruptors are circling, too. ServiceNow has publicly stated its ambition to become the CRM market leader, no-code players like Creatio are extending CRM workflows into the back office, and AI-native CRMs are courting startups. None has cracked the top five yet.
What Buyers Should Take Away
Salesforce remains the safe enterprise default, especially for organizations that want the broadest ecosystem, the deepest AppExchange integrations, and the most mature AI-agent platform.
Oracle deserves a fresh look from organizations already running Oracle ERP or HCM; its rise to #2 reflects a genuinely differentiated data story. Microsoft Dynamics 365 is still the natural choice for organizations standardized on Microsoft 365 and Azure, even as its share slips.
HubSpot continues to win mid-market and growth-stage companies on usability, faster implementation, and lower total cost of ownership. Zoho competes aggressively in the SMB segment on price and breadth of its suite.
The biggest shift since our original 2013 survey isn’t at the top. Salesforce was #1 then and remains #1 now. It’s in how the rest of the market is being reshaped. The long tail now holds nearly two-thirds of the market, the #2 spot changed hands for the first time since 2022, and a distinct AI-agent market means the next round of CRM competition may be decided less by feature checklists than by whose agents actually do the work.
Note: Market share figures vary across research firms depending on how each defines the CRM market. The IDC numbers above include sales force productivity, marketing campaign management, customer service, contact center, advertising, and digital commerce applications.